Bank acquisitions can be confusing, leaving you unsure whether to stay. Policies, fees, and services often change after an acquisition. You may wonder whether your accounts will work the same. After an acquisition, several factors determine whether to stay or go.
Customers need to think about future security, potential new fees, and service quality. Bank mergers and acquisitions frequently impact trust and financial stability. Reviewing the likely changes helps you avoid surprises. A well-informed decision protects your long-term finances.
Understanding the Bank Acquisition Process
When two banks merge or are acquired, this is known as a bank acquisition. Although notices outlining the transfer are frequently sent to customers, the specifics may seem ambiguous. An acquisition may alter daily services and banking regulations. While some customers find better digital options, others encounter new fees. Stress can be avoided by being aware of the procedure. Clients should carefully read all official correspondence from both banks.
Account security during the transition is ensured by adhering to deadlines. Sometimes there are changes to routing information or new account numbers. Verifying that automatic payments, checks, and deposits are proceeding without any problems is crucial. Updates may be necessary due to changes in branding resulting from acquisitions. Customers can better prepare if they are aware of the timeline. Making well-informed decisions lowers risk and boosts confidence. Assessing modifications ensures that financial stability endures following the shift.
Checking New Fees and Account Changes
Account terms frequently change rapidly when one bank buys another. Customers might discover fewer free services or increased maintenance costs. It becomes crucial to review the most recent fee schedule. A minor fee adjustment can result in large annual expenses. Examining account structures helps identify potential hidden fees. Customers should also see if savings interest rates are still competitive. The acquiring bank occasionally offers stronger account packages, but they come with a higher price tag.
Auto payments and direct deposits need to be closely watched. Clarity can be obtained by contacting customer service for thorough explanations. By reading the fine print, you can prevent surprises. Inquiring about online transaction limits, ATM fees, and overdraft policies helps assess fairness. The decision to stay or leave is influenced by knowledge of how the new structure affects personal finances. By carefully reviewing, knowledgeable customers prevent needless losses.
Evaluating Customer Service Quality
When one bank acquires another, customer service frequently changes. Insufficient staff training may result in a decrease in service quality. Some clients might observe slower responses or longer wait times. Service evaluation becomes just as crucial as fee reviews. Overall dependability is reflected in a bank’s reputation for support. Customers should test the helpline and in-person service. Seeing how fast employees fix issues gives important information. Employee knowledge levels can be found by posing questions regarding policies or products.
Keeping an eye on social media and customer reviews reveals actual experiences from other people. Convenience and trust are directly impacted by service quality. Small disagreements can turn into annoyance when banks merge. Good customer service gives account holders confidence that changes are managed correctly. Clarity for sustained satisfaction is provided by service evaluation. When making final decisions, customers shouldn’t overlook service quality.
Reviewing Digital Banking and Technology
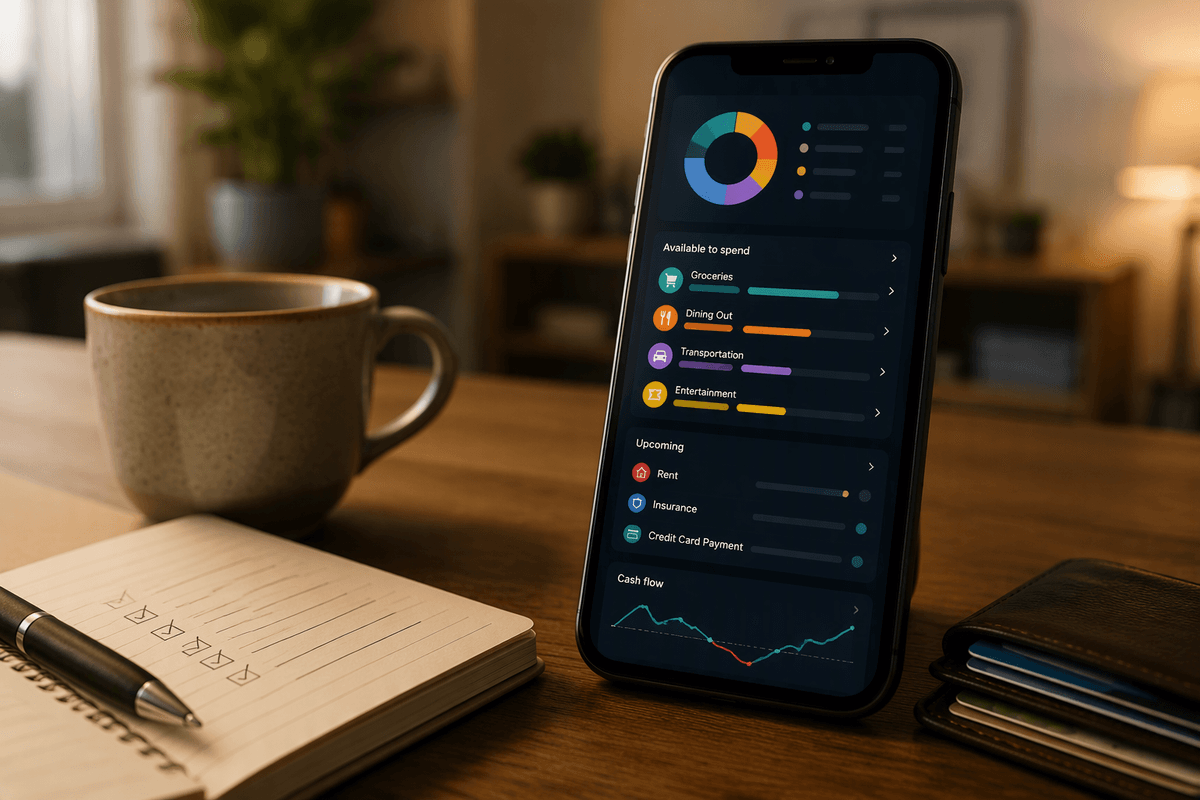
During a bank acquisition, digital tools frequently change. Customers might lose recognizable features or discover better apps. Examining the digital platform of the new bank is crucial. Daily banking is made quicker and easier with a reliable mobile app. Account alerts, fast transfers, and mobile deposits are important features. After the migration to test functions, customers should log in. It is necessary to confirm security features like two-factor authentication and biometric login.
It’s also crucial to see if the app integrates with payment systems. While some banks have downtime, others update their systems quickly. Predicting experience is aided by looking at user reviews of the new digital system. Convenience is increased by having access to financial tools like budgeting dashboards. A robust digital platform increases long-term banking confidence. Customer expectations for usability, speed, and security should be met by technology.
Considering Long-Term Financial Security
A bank acquisition can have both positive and negative impacts on long-term security. Customers need to know if the acquiring bank is stable financially. One can gain insight by reading official financial filings and news reports. Deposits are frequently better protected by a robust institution. Safety during economic fluctuations is ensured by stability. Customers are reassured by reviewing local insurance coverage or FDIC coverage.
Clients ought to assess the bank’s long-term plan as well. While some mergers prioritize short-term profit, others aim for growth and innovation. It’s important to find out if the new organization values client trust. Robust security policies protect online accounts and transactions. Being aware of long-term risks helps you avoid disappointment. A thorough assessment of financial stability aids in deciding if staying makes sense. Short-term advantages are always outweighed by security. During transitions, safeguarding funds is the top priority.
Making the Final Decision
Customers must choose whether to stay or go after evaluating costs, service, technology, and security. The choice is based on personal priorities. While some clients value affordable prices, others place a higher value on superior service. Choices are also influenced by financial stability and digital features. Making a checklist makes comparing old and new terms easier.
Additionally, customers ought to evaluate offers from rival banks. Better incentives or benefits might be offered by switching banks. But staying could also bring stability and continuity. The choice is made clearer by weighing costs, convenience, and trust. Advice can also be obtained by speaking with family members or financial advisors. Taking prompt action after making a decision helps to prevent confusion. Proper account closure ensures seamless transitions. Financial peace of mind is ensured by making a final decision with confidence. The best decision is always supported by careful analysis.
Conclusion:
Bank acquisitions impact customers in several significant ways, including fees and service quality. New account structures should be reviewed to avoid unpleasant surprises. The decision is influenced by digital banking, customer service, and financial security. Long-term stability should always be the main consideration when deciding whether to stay or go. Convenience is not as important as protecting personal finances. Future issues can be avoided by using careful evaluation. Customers who conduct in-depth research come to wiser conclusions. Making thoughtful and prudent decisions always improves financial health.