A Stronger Profit Can Hide a Weaker Business
A company can report a higher net margin and still offer the weaker business. The number may reflect cheaper borrowing, a lower tax bill, or a one-time gain rather than stronger day-to-day operations. That creates a practical problem for investors comparing firms that appear similarly profitable: the headline percentage may reward financial structure instead of business quality. A manufacturer with steady pricing power can look less successful than a rival benefiting from unusual income, even when its core operations are healthier.
Operating margin helps separate those operating economics from financing and tax effects, but it does not answer every investment question. Net margin still matters when assessing what ultimately reaches shareholders. The comparison becomes useful only after identifying which margin is explaining the difference.
Start With the Business Before the Balance Sheet
That investigation usually starts with the income statement, before debt and tax decisions blur the picture. Operating margin compares operating profit with revenue, showing how much the company keeps from selling its products or services after paying the costs required to run the business. It brings pricing, labor, materials, production, and administrative discipline into view. If one retailer earns a 12% operating margin and another earns 7%, the gap points first to differences in pricing power, cost control, or product mix.
The measure is not perfectly clean. Companies can classify expenses differently, and restructuring charges or acquisitions may distort a single period. Still, it gives investors a more useful starting point than net margin when the question is whether the underlying business is working. A highly leveraged company may post a lower net margin because interest consumes a large share of operating profit, while an almost debt-free rival may appear stronger for reasons unrelated to its products or customers. Looking at operating performance first does not make financing irrelevant; it prevents financing choices from deciding the initial judgment about the business itself.
Net Margin Adds Reality—and More Noise
Once operating performance is separated out, net margin brings the rest of the financial picture back into view. It shows how much revenue remains after operating costs, interest expense, taxes, and other items have been recorded. That makes it closer to the profit ultimately available to shareholders. A company with a solid operating margin may still produce a modest net margin if heavy debt payments absorb the difference. In that case, the lower figure is not meaningless noise; it identifies a real claim on the business’s cash generation.
The difficulty is that net income can also be moved by events that say little about repeatable performance. A tax benefit, asset sale, investment gain, legal settlement, or restructuring charge may lift or depress the result for one reporting period. Timing adds another constraint: a lower tax rate or unusual gain can make this year’s net margin look attractive even when the benefit is unlikely to recur. Investors therefore need to ask whether the gap from operating margin reflects a lasting financing or tax burden, or simply a temporary accounting effect. Net margin adds realism, but without the notes and prior periods, it can make a weak comparison look precise.
Why Two Apparently Profitable Companies Diverge
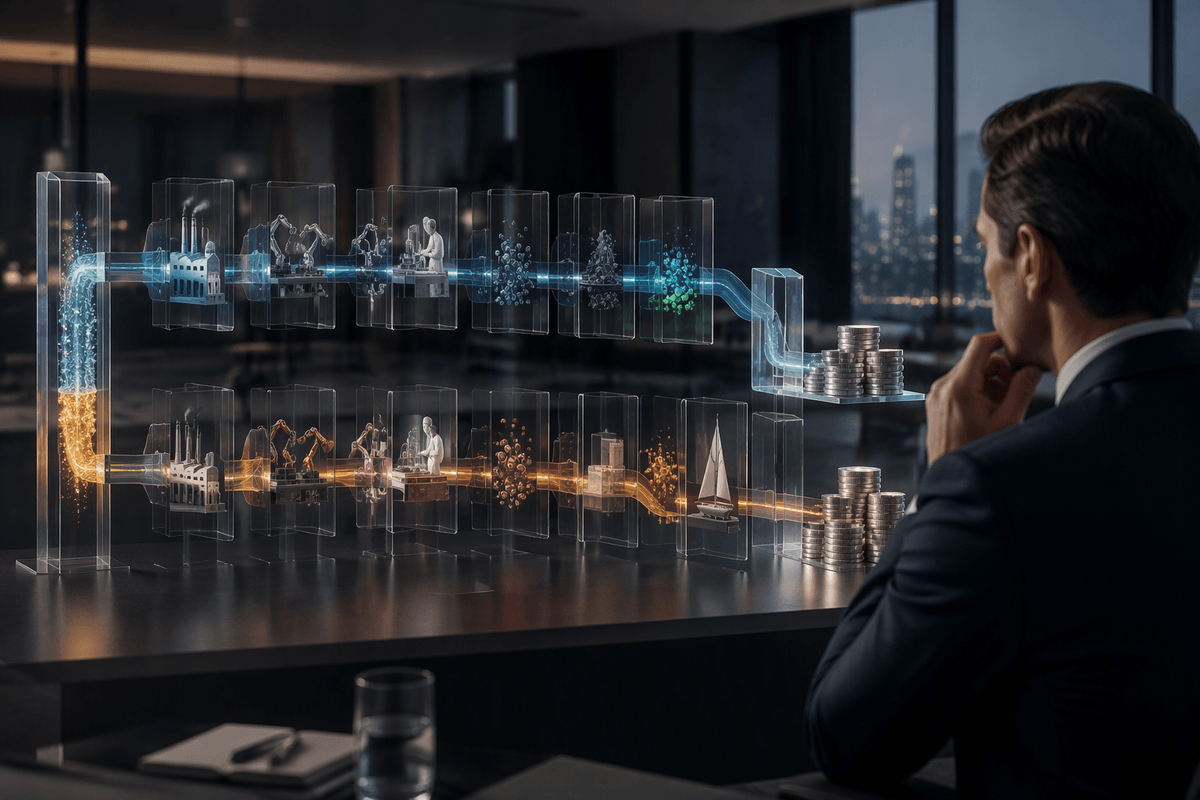
That distinction becomes clearer when two companies post similar net margins but reach them through different paths. One may earn a strong operating margin and lose part of it to interest expense, while the other may run a thinner business but carry little debt and pay less tax. Their final profits can look alike even though their exposure to refinancing costs, pricing pressure, or weaker demand is very different.
The reverse comparison can be just as misleading. A company with a higher net margin may owe its advantage to a temporary tax benefit or an asset sale, while a rival’s lower result reflects recurring investment in production, research, or expansion. The timing of those costs creates another constraint: the spending may depress current profit while supporting future sales, making a single year’s margin a poor guide to business quality. Investors comparing the two need to trace the gap from revenue down to net income, asking which differences are operational, which come from capital structure, and which are unlikely to repeat. The apparent winner can change once those effects are separated. A similar bottom-line result, therefore, does not mean similar durability.
Choose the Margin That Fits the Question
Once those paths are separated, the useful margin depends on the decision being made. If the question is whether the products, services, or stores generate attractive economics, operating margin deserves priority. It limits the effect of debt, taxes, and unusual gains, making comparisons between businesses with different financing choices more consistent. That view is especially important when an investor is testing pricing power or cost control. The constraint is comparability: different expense classifications, acquisitions, or restructuring charges can still weaken the signal.
Net margin fits a different question: how much of each dollar of revenue is left after every major claim has been paid. It matters when debt levels, tax exposure, or shareholder earnings are central to the decision. A company may have excellent operations but too much interest expense to produce dependable profits. Yet relying on net margin alone can mistake a temporary tax benefit for durable improvement. The practical choice is not to declare one measure superior. Use operating margin to judge the engine, then use net margin to test what that engine actually delivers after the financial structure takes its share.
Check Whether the Difference Can Last
That comparison still needs a time test. Review several periods to see whether the gap between operating and net margin repeats, widens, or disappears. A persistent difference may reflect structural debt costs, a stable tax position, or a business model with consistently higher operating expenses. A sudden change deserves more caution: refinancing, an asset sale, a tax adjustment, or restructuring charge can distort one year.
The constraint is imperfect timing. Even a genuine investment in capacity or research may weaken current margins before producing results. Durability therefore depends on both repetition and cause, not simply on which company reports the larger percentage today.
A Better Profitability Judgment Uses Both Measures
The clearest judgment comes from reading the two margins together rather than choosing a permanent winner. Operating margin shows whether the core business can generate profit before financing and tax decisions intervene. Net margin shows how much of that result survives for shareholders. When both improve across several periods, the evidence for stronger profitability is more convincing. When they move apart, the gap becomes the subject of the analysis.
That approach still requires restraint. Debt costs, tax changes, unusual gains, and investment spending can alter the final result, while classification choices can weaken operating comparisons. The useful conclusion is narrower: operating margin tests business strength, net margin tests delivered profitability, and the difference between them reveals what may prevent today’s profit from lasting.