Your Family Changed, but Did Your Policy?
A life insurance policy can sit untouched while the household around it changes. A wedding brings shared bills; a new baby adds childcare costs; a separation leaves two homes to support. The paperwork may still feel settled because the premium keeps getting paid. Then someone asks who is listed to receive the money, and the answer comes from memory rather than the policy. There may be a familiar name on file, but a different person now carries the household’s financial load.
Start by checking the beneficiary designation with the insurer. Compare the recorded choice with today’s dependents and obligations before deciding whether that name still fits.
The Person You Expect May Not Inherit
A familiar name on that record can hide a mismatch: the person listed may not be the person the family expects to receive the money. A life insurance beneficiary designation generally takes priority over instructions in a will. Leaving everything to a current spouse in the will does not, by itself, replace someone named on the policy.
After divorce, avoid assuming either that an ex-spouse stays entitled or that the designation disappears. State law, policy type, and court orders can affect the result. Ask the insurer what applies, and seek legal guidance if obligations are unclear. Before choosing a replacement, separate two questions: who is entitled under the existing paperwork, and who would need the payment now?
Who Would Need the Money Most Immediately?
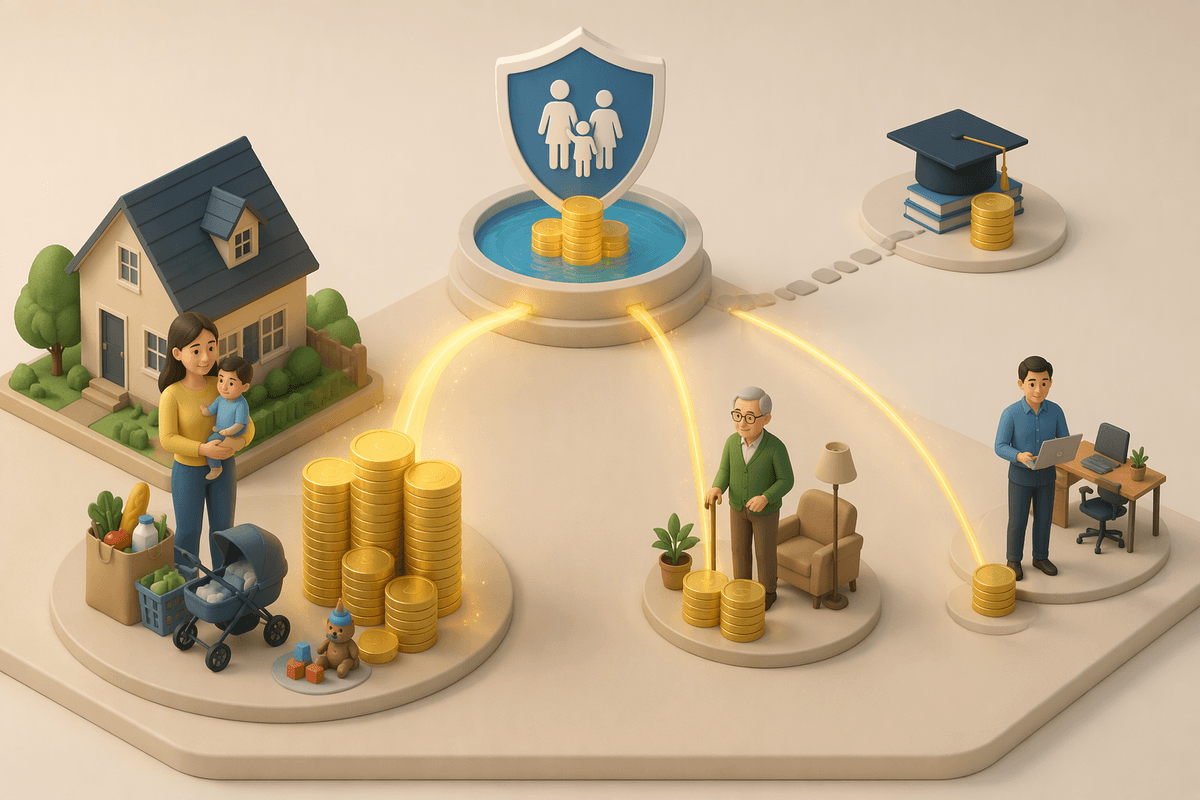
Start with the first few months of bills: rent or mortgage payments, groceries, childcare, and support sent to a parent. List who would have to cover each expense without the income or care currently provided. Life insurance needs include replacing income and paying for care—not simply leaving an inheritance.
Suppose a spouse has little savings and would need paid childcare to keep working, while an adult sibling has steady earnings and no shared bills. An equal split might feel fair, but test what each share would actually cover. Compare monthly shortfalls, available savings, and how long help would be needed. Keep immediate household costs separate from later goals, such as education, so a distant expense does not crowd out next month’s rent.
Before settling on names, ask who would handle those payments and whether that matches the person intended to benefit. If the money is mainly meant to support a young child, the choice is not finished: deciding who should receive and manage it needs its own attention.
Naming a Child Creates Another Decision First
The adult covering childcare bills may not automatically have authority to collect money left directly to the child. Insurers generally cannot pay a death benefit straight to a minor; payment may require a legally authorized guardian for the child’s money or be held until the child reaches legal age. That guardian can be different from the person raising the child. A name on the form alone may therefore leave daily expenses waiting.
Before entering the child’s name, ask the insurer about naming an adult custodian under state law or directing payment to a trust. These are arrangements for managing the child’s money, not simply alternative names. A trust can set out who manages the funds, which expenses they cover, and when the child receives control. Compare the setup and ongoing costs with the amount of coverage, and ask an estate-planning attorney which arrangement fits the intended use.
Then consider the adult’s actual capacity: keeping records, handling requests, and making spending decisions while grieving. Someone willing to raise a child may not want that additional responsibility. The roles can be separated. Discuss the work before naming anyone, and ask who could take over if the first person becomes unavailable.
Build a Backup Beyond Your First Choice
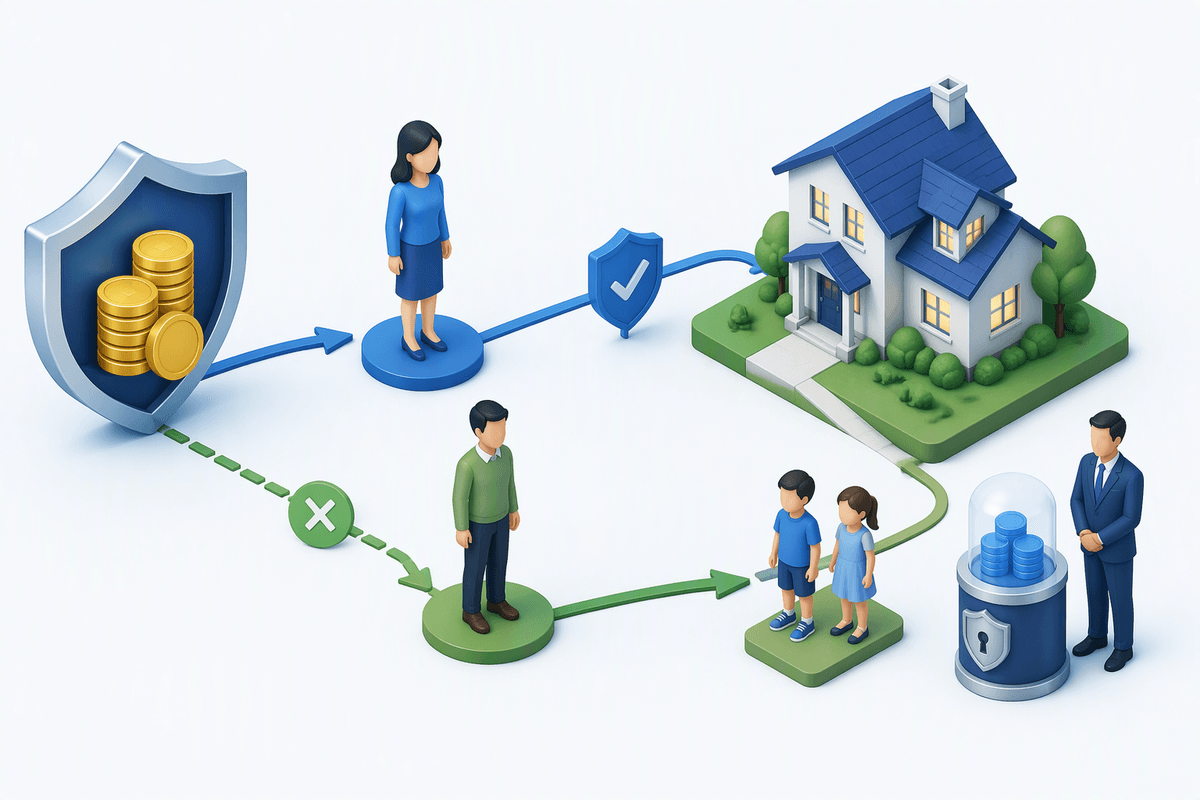
That replacement needs a clearly defined role. Ask the attorney to address a successor for managing the child’s money separately from the policy’s backup recipient. The primary beneficiary is first in line for the death benefit; a contingent beneficiary generally receives it if no primary beneficiary survives. Naming both provides another route for payment, but the backup must still fit the family’s needs.
Suppose a spouse is the sole primary beneficiary. If that spouse dies first, would the backup choice still support the children’s housing and care? Work through that possibility before entering names. If several people share either level, follow the insurer’s instructions for allocating shares; each level should total 100%. Ask what happens if nobody named survives. Without an eligible recipient, payment may go to the estate, potentially adding delays when household bills cannot wait.
Make the Change Official Before Life Moves Again
Once the backup choice is settled, put the full arrangement through the insurer’s change process. Use its current form or online account rather than leaving the decision in a family note. Read whether the request replaces every existing beneficiary: Guardian, for example, requires names that should remain to be included again. Leaving a spouse off while adding a child could undo part of the plan.
Gather the details requested before submitting. New York Life’s form asks for identifying and contact information to help locate recipients and pay claims promptly. Check names against records, and follow the insurer’s instructions for any trust or custodian already chosen. An unfamiliar field is worth a call rather than a guess made to finish the paperwork.
After submission, ask for written confirmation of the updated names, shares, and effective date. Keep that confirmation with the policy and save the submitted request. Set a follow-up reminder if nothing arrives within the insurer’s stated timeframe. The task is not merely sending the form; it is checking that the recorded choice matches the decision.
Leave With a Choice You Can Maintain
Before filing the confirmation away, add a short note about why these people and shares fit the household now. Include the bills the money is meant to cover. That gives the next review a starting point beyond remembering names.
Set a yearly reminder, and revisit the choice sooner after a birth, separation, death, or change in financial support. Review need not mean replacement; check whether the arrangement still fits. If time is tight, start with what changed and who now carries the expense. The choice does not have to anticipate every future household—just remain one that can be checked and maintained.